Health Savings Accounts — the Triple Tax Threat!
March 10, 2026
The wisdom of funding specific needs when markets are high
By Clark Troy
I just bought a new car a couple of weeks back, my first new car purchase ever.* It’s a beautiful new Toyota Prius plug-in hybrid, pretty much the car of my people, as a Chapel Hill native. We needed a fresh vehicle because the 2010 Prius we had bought in 2012 as a wee low-mileage thing and had christened “Beatrice” had come to that inflection point all cars reach where the cost of repairs exceeds its value. Our mechanic looked me squarely in the eye and delivered the sad verdict.d away in confused frustration. Others simply walk away.
When discussing capital markets we often talk about not wanting to buy at the top or sell at the bottom, while noting that paradoxically one never knows when the actual tops and bottoms are, except retrospectively. Which is absolutely true. You don’t know when a market has reached its tippy top in a given market cycle.
But while knowing “the peak” of a cycle is very hard, knowing when “a peak” has been reached is the easiest thing possible. And over the last decade the S&P 500 has hit new all-time highs some 204 times, which is a high number given that we’re only half way through the decade but isn’t all that surprising given the propensity of both Democratic and Republican administrations to run huge deficits and therefore maintaining a large monetary supply and also the general perception — which has gone away only in the last year and change — that the USA was the default best place for global investors to park wealth.
Alone amongst the firmament of IRS-defined account types, the HSA offers tax benefits at each moment of the income tax lifecycle. Contributions are deductible from income. Investments grow tax-free. If spent on qualified healthcare expenses, no taxes are due upon withdrawal. Let’s compare with a few of the most popular account types.
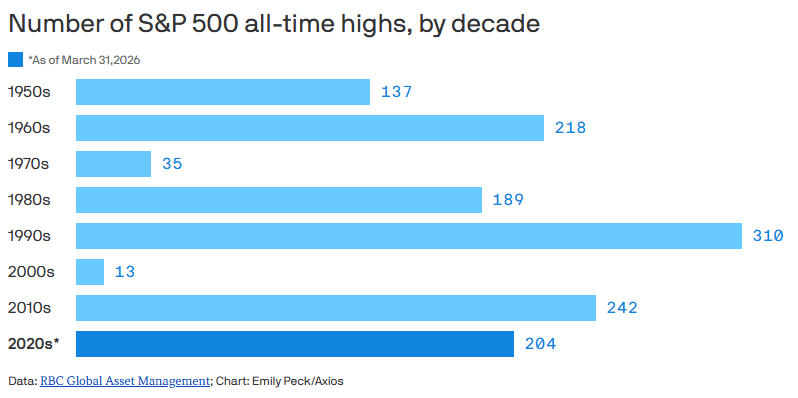
Source: Axios, 4/17/2026: “The S&P 500 Keeps Hitting All-Time Highs”
And when markets are at “a” peak, well that’s a great time to buy things that you need or just want. Like a car. Or a couch. Or a bathroom upgrade.
At the same time, we reasonably fear what is to come and our ability to maintain our current lifestyle as the future unrolls before us. How much money will we need to make it through to the end? How long will we live? How much money can we expect to earn on our investments through the decades? Good questions all, each of them precisely unanswerable in the present though all with guideposts if we’re willing to do research, observe ourselves honestly, and write things down. The only iron rule of finance is that those who earn and save more than they spend for most of their lives end up well off.
That sounds like a good place to end, but I can’t help but to loop back and look at the chart above with a couple of observations. First off, look how few all-time peaks the S&P 500 hit during the 2000s, and the 1970s for that matter. After the booyah 90s followed upon the post-Cold War End of History and the early, ecstatic days of the internet and the Nifty Fifty of demographically-driven expansion in the 1960s, markets had long rough periods. We know that history doesn’t repeat but it often rhymes. Could the 2030s also be a period of protracted challenges for the markets? They could. Nobody knows.
If that does happen, the 2030s should be a fine time to mend nets and for those earning salaries to contribute to 401ks, as were the aughts. For me, the decade to come should be a great time to own a relatively low-mileage Toyota and enjoy the PBJs that often comprise my breakfast, as will be the case today.
*I would never have contemplated buying new without the express counsel of my car-buying agent, who assured me that on this occasion the deal on the new car was better than any deals available on used cars for some nerdlinger technical reason long since jettisoned from memory.
This article originally appeared on Straight Edge Finance. Click here to read more from Clark Troy.